How Cash-Flow Forecasting Helps You Prepare for Upcoming Expenses
PAGE
By PAGE Editor
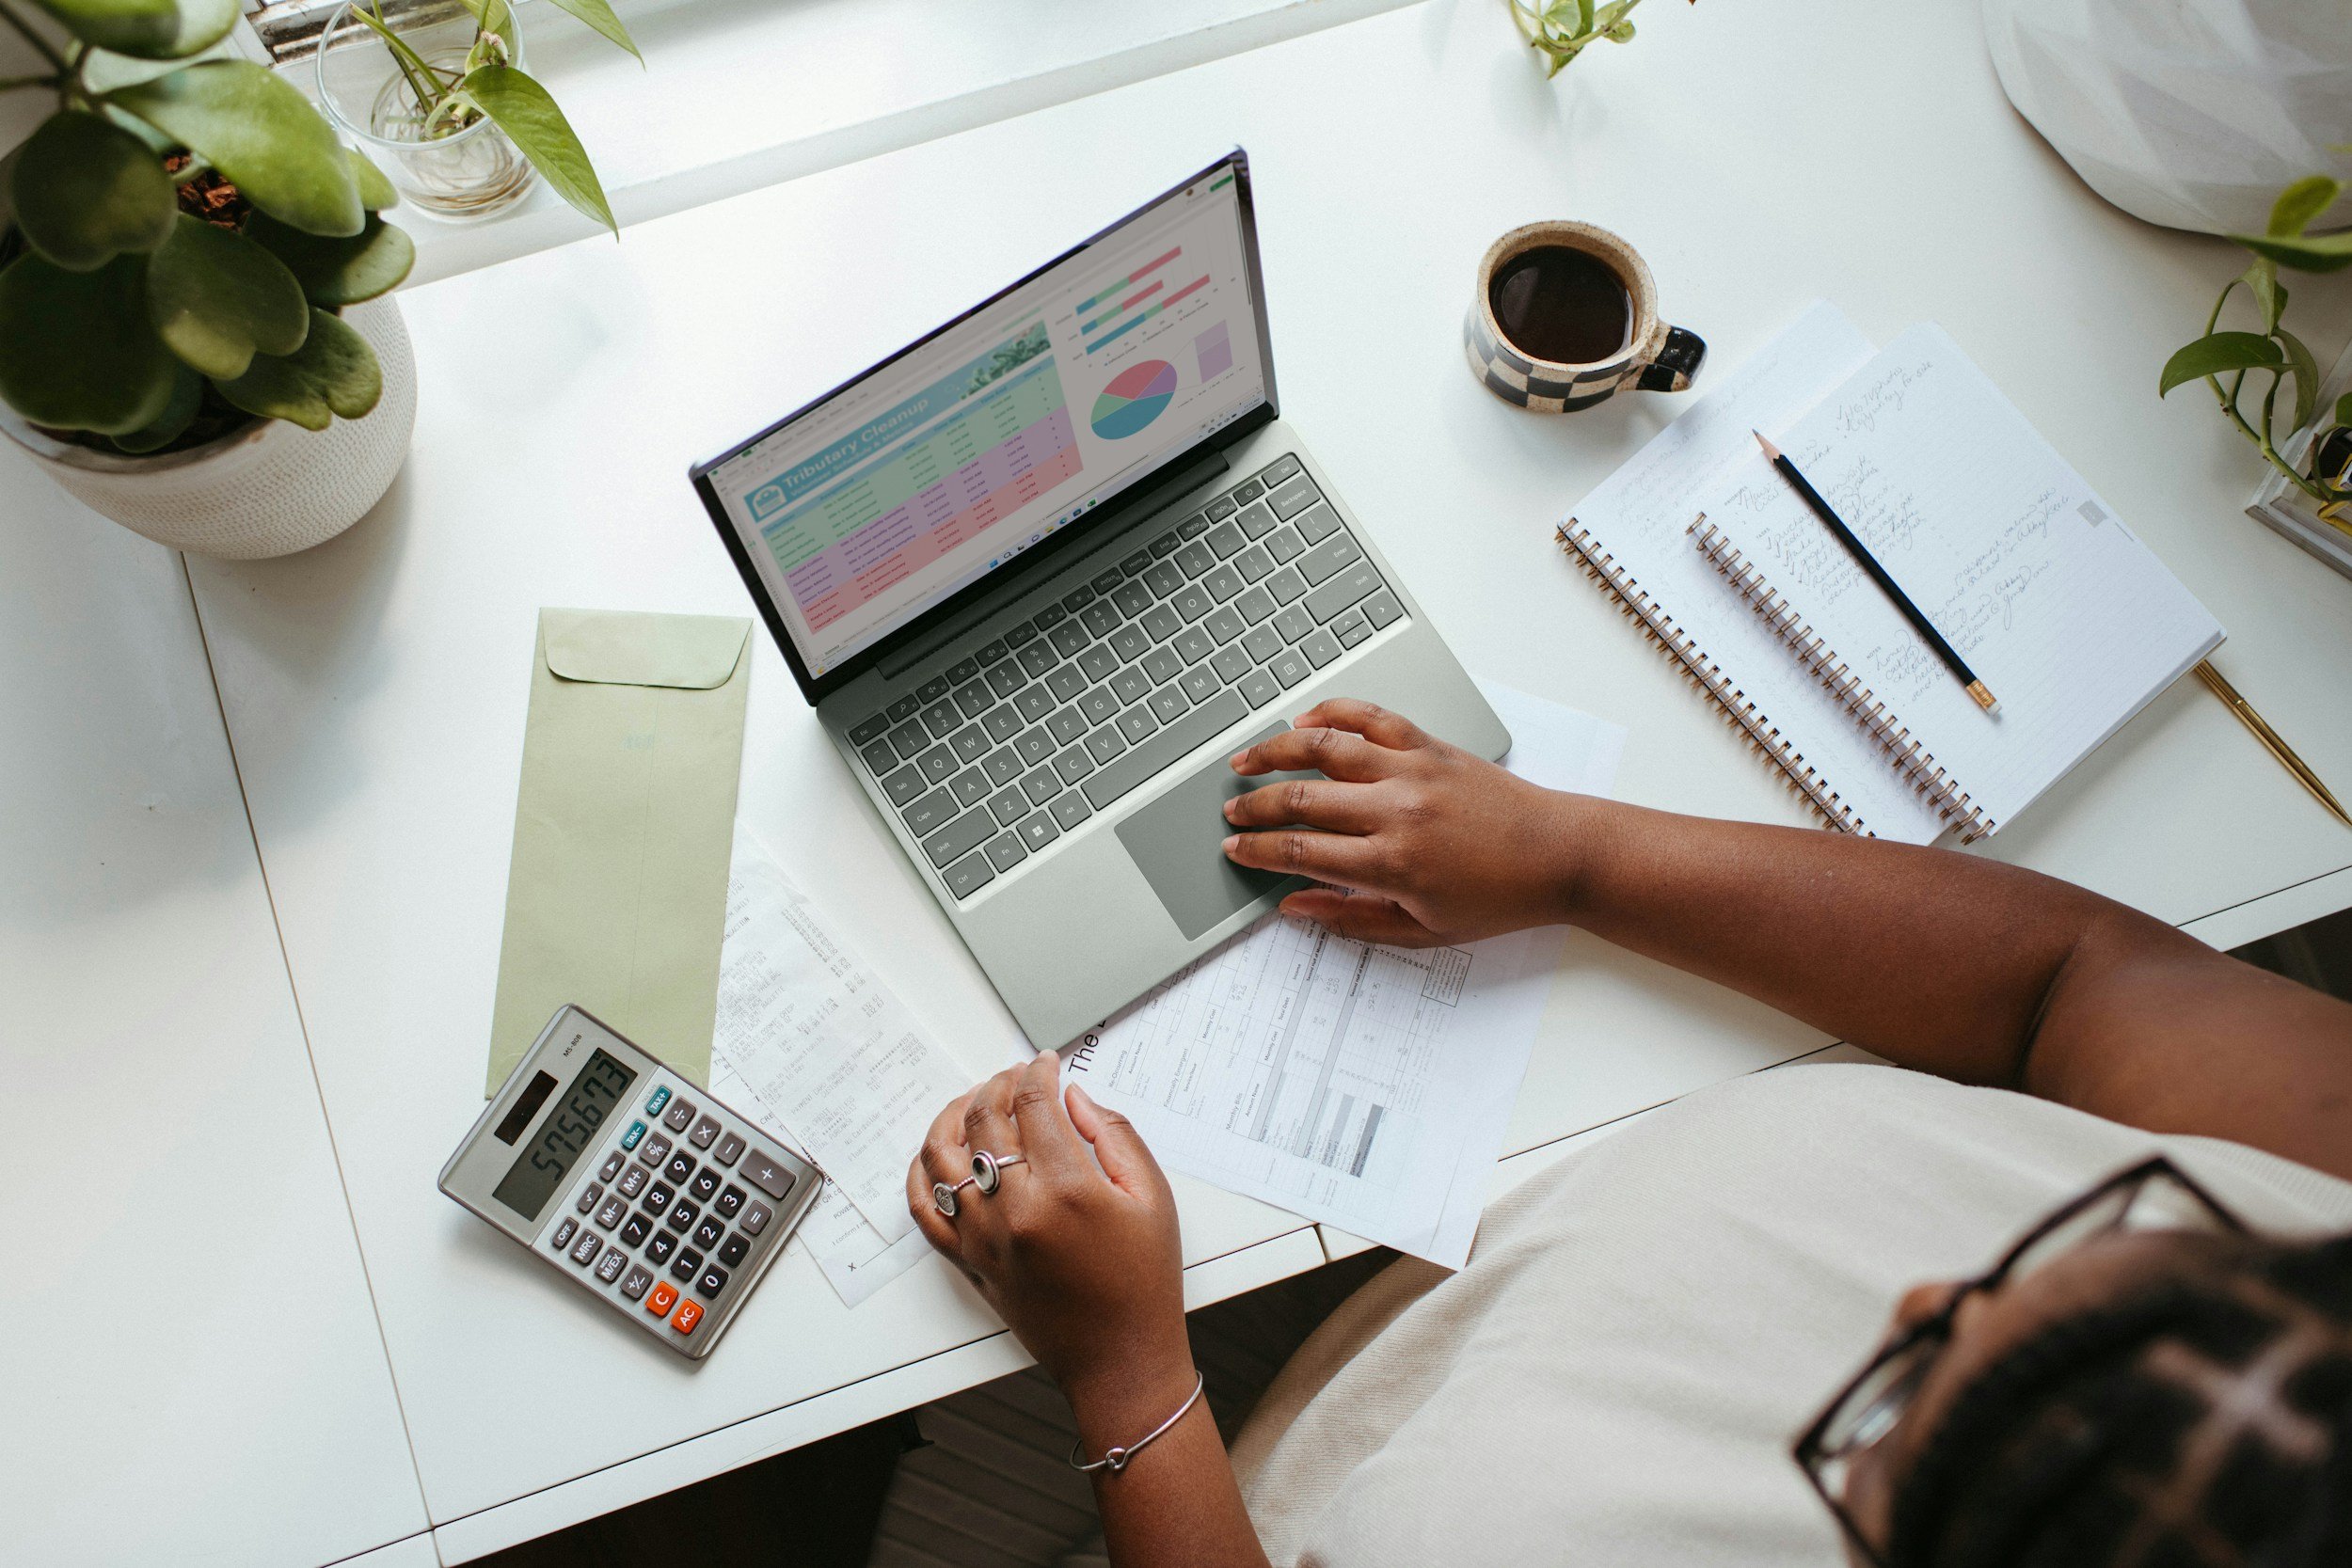
A monthly budget tells you whether income and expenses fit overall. A cash-flow forecast adds another question: when will the money come in, and when will it need to leave?
That timing matters when several bills, savings contributions, or large expenses cluster before the next paycheck.
Start With Timing, Not Just Totals
The CFPB's cash flow budget tracks the timing of income and expenses week by week so periods of potential shortfall are visible before they happen.
A household can earn enough for the month and still run tight during one week if bills are concentrated early.
Use Current Spending as the Baseline
Iowa State Extension's Money Smart resources include income trackers and bill calendars that help households see what is due and when. Timing matters even when the monthly totals look manageable.
A forecast is more useful when it starts from realistic numbers rather than idealized category targets. If utilities or groceries have been running higher, the future view should reflect that until there is evidence the pattern has changed.
Add Known Future Costs
Include bills already scheduled, annual expenses, planned purchases, travel, school costs, and other items that will affect cash even if they are not due this month.
A forecast becomes especially helpful when a large expense is predictable but falls between normal pay cycles.
Include Goal Contributions Too
When future cash flow includes savings targets, Monarch's financial planning app can represent those goals with target amounts and planned monthly contributions tied to specific accounts.
Those contributions should appear in the cash-flow picture just like bills. Otherwise the forecast may overstate how much money is available for ordinary spending.
Use the Forecast to Move Decisions Earlier
The best time to spot a shortfall is before it happens. If one future month is overloaded, you may be able to move a contribution, save more in an earlier month, request a different bill date, or postpone a discretionary expense.
Forecasting is useful because it turns a future cash problem into a current planning decision.
Some future numbers will be exact and others will be estimates. Rent may be known to the dollar, while utilities, groceries, or travel costs are not. A forecast can still be useful if those uncertain numbers are based on recent history and updated as better information becomes available.
It helps to mark which assumptions are especially uncertain. If an upcoming repair could cost anywhere from $500 to $1,000, use a reasonable working estimate and leave room for the range rather than pretending the final amount is known.
The purpose of the forecast is not to prove what the bank balance will be on a specific date months from now. It is to spot periods where the current plan looks tight enough to deserve attention.
At the end of each month, compare the expected cash flow with what actually happened. If the same category is consistently off, update the assumption. A forecast gets more useful when it learns from recent results instead of carrying old estimates forward indefinitely.
A forecast can also show when a goal contribution is technically affordable for the month but poorly timed within it. Moving the contribution a few days, splitting it across paychecks, or building a small checking buffer may solve the issue without lowering the goal itself. That is one of the advantages of looking at timing rather than only monthly totals: some shortfalls are scheduling problems, not spending problems. The same logic applies to income. If a bonus or freelance payment is uncertain, keep it separate from income the plan depends on until it actually arrives. That keeps the forecast from solving a future shortfall with money that may not show up.
HOW DO YOU FEEL ABOUT FASHION?
COMMENT OR TAKE OUR PAGE READER SURVEY
Featured
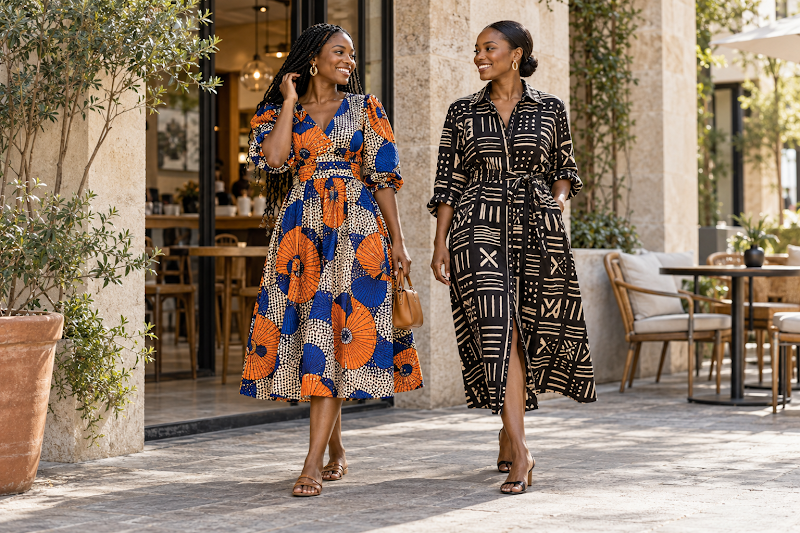
Flyknit and leather sit at opposite ends of the handbag world, and buyers get pushed into picking a side too early. One sounds modern and light. The other sounds premium and safe.