Sinkhole Disclosures in Florida: What Central Florida Homeowners Need to Know Before They Try to Sell
PAGE
By PAGE Editor
Florida is the most sinkhole-prone state in the country. If your property has any sinkhole history — even a repaired one — the disclosure rules, insurance complications, and buyer financing obstacles can derail a sale before it starts.
Sinkholes are one of the most common deal-killers in Central Florida real estate. Not because the properties are unsellable, but because most sellers don't understand how Florida's disclosure requirements, insurance landscape, and buyer lending rules interact — and by the time they find out, the deal is already falling apart.
If you own a home in Central Florida and you're planning to sell, you need to know three things before you list: what you're legally required to disclose, how sinkhole history affects your buyer's ability to get financing and insurance, and what your realistic options are when a traditional sale isn't working. This guide covers all three.
Florida's Sinkhole Geology: Why This Is a Central Florida Problem
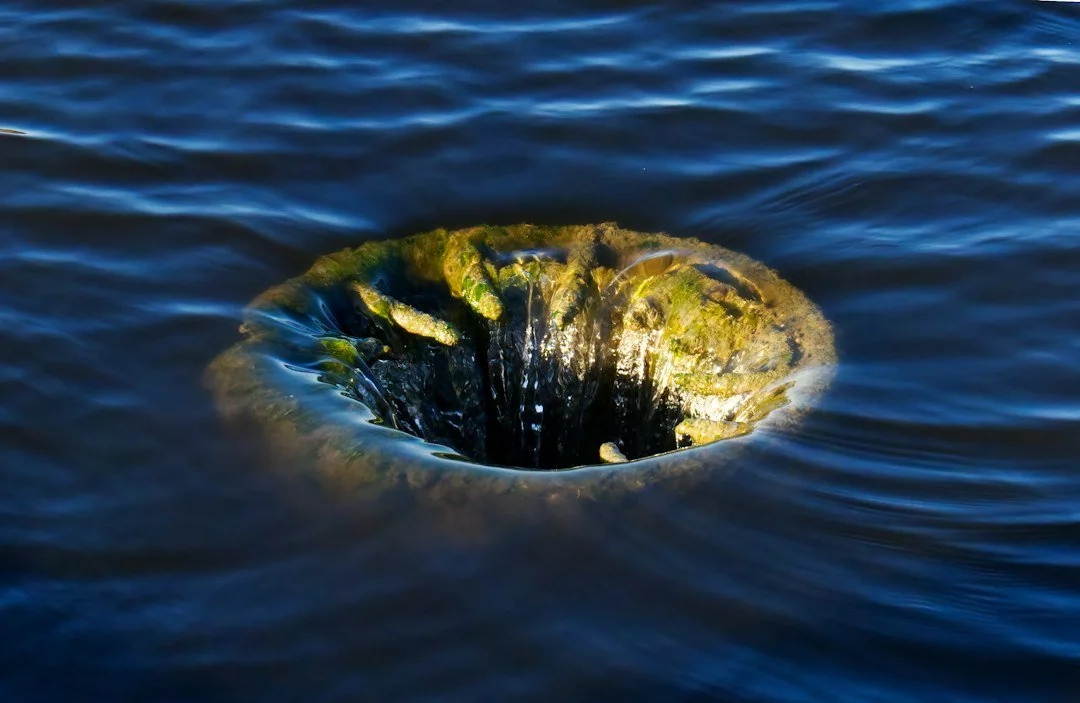
Florida sits on a foundation of porous limestone — the kind of bedrock that dissolves over time when groundwater flows through it. That dissolution creates underground voids, and when the surface soil can no longer support its own weight over those voids, the ground collapses. That's a sinkhole.
The highest-risk area in the state is a belt known as "Sinkhole Alley," stretching through Pasco, Hernando, Hillsborough, Marion, and Pinellas counties in west-central Florida. But Central Florida isn't exempt. The Florida Geological Survey has documented sinkhole activity across Orange, Seminole, Osceola, Lake, and Volusia counties. Volusia County alone recorded 58 incidents in the FGS's 2008 sinkhole map, with concentrations along the U.S. 17-92 corridor near DeLand and Deltona. The Florida Department of Environmental Protection's more recent data shows 42 incidents in Volusia County between 2004 and 2023, with Deltona, DeBary, and Orange City among the most affected communities.
This isn't theoretical risk. Hurricane Milton's heavy rainfall in 2024 triggered multiple collapses in Volusia County, including events on U.S. 17-92, Threadgill Place, and Tremont Drive. Heavy rain accelerates the erosion of karst terrain — the limestone and sand layers beneath Central Florida's surface — and turns dormant voids into active sinkholes.
For homeowners, the question isn't just whether a sinkhole could form on their property. It's whether one already has — and what that means when they try to sell.
What Florida Law Requires You to Disclose
Florida's sinkhole disclosure obligations come from two overlapping legal sources, and sellers need to understand both.
The Johnson v. Davis Duty
Florida doesn't have a single mandatory seller disclosure form like some states do. Instead, the seller's obligation to disclose comes primarily from a 1985 Florida Supreme Court decision called Johnson v. Davis. That case established a clear rule: sellers must disclose any known facts that materially affect the value of the property and are not readily observable by the buyer.
Sinkhole activity — past or present — clearly falls under this standard. If you know your property has experienced ground settlement, foundation cracking caused by subsurface activity, or any other sinkhole-related issue, you are legally required to disclose it. This obligation exists whether you sell through an agent, sell by owner, or sell as-is to a cash buyer. The "as-is" label means the buyer is accepting the property's condition — it does not eliminate your duty to share what you know.
Florida courts have held sellers liable for concealment even years after closing. Trying to hide or downplay a sinkhole issue isn't just ethically wrong — it's a legal liability that can follow you long after you've cashed the check.
The Statutory Insurance Disclosure Under F.S. § 627.7073
The second layer is more specific. Under Florida Statute § 627.7073, if an insurance company has ever paid a sinkhole claim on your property — whether you filed it or a previous owner did — you are required to disclose two things to the buyer before closing: that a sinkhole claim was paid, and whether the full amount of the insurance proceeds was used to repair the sinkhole damage.
This statute also requires insurers to file sinkhole investigation reports with the county clerk of court. That means the sinkhole history is a matter of public record. Even if a seller tries to omit it, a thorough title search or a buyer's own research through the Florida Geological Survey database or the county clerk's records will likely surface it.
The practical takeaway: you cannot hide a sinkhole. The records exist. The law requires disclosure. And any attempt to conceal the history creates legal exposure that far exceeds whatever short-term price advantage you might gain.
How Sinkhole History Kills Financed Deals
Here's where the reality gets difficult for sellers. Even when you disclose everything properly and the buyer wants to move forward, the deal can still collapse — because the buyer's lender and insurance company have their own requirements, and sinkhole history triggers all of them.
The Lender's Inspection Requirement
When a buyer applies for a mortgage on a property with a known sinkhole history, the lender will typically require a sinkhole inspection or geotechnical evaluation before approving the loan. These inspections aren't cheap — they range from $500 to $4,000 or more depending on the scope — and the results can determine whether the lender will finance the purchase at all.
If the inspection reveals active sinkhole activity, unrepaired damage, or soil conditions that suggest ongoing instability, the lender may decline to fund the loan. That means the buyer can't close, and the deal falls apart — often after weeks of waiting.
The Insurance Problem
Florida law requires every residential property insurance policy to include coverage for something called Catastrophic Ground Cover Collapse (CGCC). This sounds comprehensive, but it isn't. CGCC coverage only applies when all four of these conditions are met simultaneously: the ground collapses abruptly, a visible depression appears, the home suffers structural damage including foundation damage, and a government agency condemns the structure and orders it vacated.
Most sinkhole damage doesn't meet that standard. The far more common scenario — gradual settlement, cracking foundations, walls separating, doors that won't close — requires separate sinkhole loss coverage, which is an optional endorsement purchased for additional premium. Insurance companies can require a pre-inspection before issuing this coverage, and they can decline to offer it based on the property's history or location.
For buyers trying to purchase a home with sinkhole history, the insurance math can get ugly. If the buyer can't obtain affordable sinkhole coverage — or if the only available coverage carries a deductible of 10% of the dwelling value — the total cost of ownership becomes prohibitive. Some insurers simply won't write a policy at all for properties with prior claims. When that happens, the buyer's lender won't fund the loan, and the sale is dead.
The Appraisal Gap
Even when financing and insurance are technically available, sinkhole history affects appraised values. Appraisers adjust for known subsurface issues, and comparable sales of sinkhole-affected properties tend to trade at significant discounts. If the appraisal comes in below the contract price, the buyer either needs to make up the difference in cash or renegotiate — which puts the seller right back at the starting line after weeks of waiting.
What This Means for Sellers Who Need to Move
The combination of disclosure requirements, insurance complications, and financing obstacles creates a specific problem for Central Florida homeowners with sinkhole-affected properties: the pool of buyers who can actually close on your home shrinks dramatically.
Traditional buyers — the ones who need a mortgage — are subject to their lender's sinkhole inspection requirements and their insurer's coverage decisions. Neither of those things is in the seller's control. A seller can price the home fairly, disclose everything honestly, and still watch deal after deal fall through because the buyer's financing falls apart at the last minute.
This is exactly the scenario where cash buyers become a practical option. A cash buyer doesn't go through a mortgage lender, which means there's no lender-mandated sinkhole inspection, no insurance requirement that has to be satisfied before closing, and no financing contingency that can collapse at the eleventh hour. The buyer evaluates the property's condition — including any sinkhole history — and makes an offer based on what they find. If the seller accepts, the closing proceeds on a set date without the lender and insurer obstacles that derail traditional sales.
For homeowners in Volusia County — particularly in communities like Deltona, DeBary, and Orange City where sinkhole activity has been documented — the math often favors certainty over listing price. Across 42 seller transactions that Eagle Cash Buyers documented in 2026, roughly one in five sales involved a title or documentation problem that had to be resolved before closing, and timing mattered more than price to a meaningful share of sellers. These are sellers who contacted a cash buyer, not a representative sample of all home sellers, but the pattern is relevant: when conventional paths stall, a guaranteed cash close on a date you choose has real value.
If your Deltona home has a sinkhole disclosure, an insurance complication, or a history that makes traditional financing difficult, the option to sell your house fast in Deltona, Florida through a direct cash sale removes the obstacles that kill financed deals. No lender-required inspections, no insurance contingencies, no appraisal gaps. The agreed price goes to the seller intact — no closing costs, no agent commissions, and no fees deducted at closing beyond the seller's own mortgage payoff and any recorded liens.
Repaired Sinkholes: You Still Have to Disclose
A common misconception among Florida sellers is that a repaired sinkhole is no longer a disclosure issue. That's wrong.
Florida law requires disclosure of prior sinkhole activity and prior insurance claims regardless of whether repairs have been completed. The repair addresses the physical problem — it doesn't erase the history. A buyer is entitled to know that the property experienced sinkhole activity, that a claim was filed, and whether the insurance proceeds were fully used for repairs.
In fact, the quality of the repair itself becomes part of the disclosure conversation. Sinkhole remediation in Florida typically involves either compaction grouting (injecting material underground to fill voids and stabilize the soil) or underpinning (installing steel piers to support the foundation). Both methods are well-established, but they vary in cost, effectiveness, and longevity — and a buyer's engineer may want to review the remediation report before the lender will approve financing.
If the repair was done properly and the remediation report is clean, it can actually help the sale by demonstrating that the issue was professionally addressed. But if the repair was incomplete, undocumented, or the remediation report raises questions about ongoing stability, it becomes another obstacle to closing.
The lesson: keep your remediation records. Engineering reports, contractor documentation, permits, and insurance correspondence related to sinkhole repair are all materials a buyer or their lender may request. Having them organized and available speeds up the process and builds confidence with the buyer.
How to Research Your Own Property's Sinkhole History
Before you list your home — or before you accept any offer — you should know what's in the public record about your property's sinkhole history. Here's where to look:
The Florida Geological Survey subsidence database. The FGS maintains a searchable database of reported sinkhole incidents across the state. This is the starting point for understanding whether your property or nearby properties have documented activity.
The county clerk of court records. Under F.S. § 627.7073, insurers are required to file sinkhole investigation reports with the county clerk. A search of these records will reveal whether a sinkhole report has ever been filed on your property's address.
Your own insurance history. Review your homeowners insurance records and claims history. If you've ever filed a claim related to foundation cracking, ground settlement, or sinkhole activity, that information is part of your property's record — and it's something you'll need to disclose.
Your property appraiser's records. While the property appraiser's office doesn't track sinkholes directly, significant changes in assessed value or notes about structural issues in the property record can signal past events worth investigating.
A professional geotechnical evaluation. If you suspect sinkhole activity but don't have documentation, a licensed geotechnical engineer can conduct a subsurface investigation. This typically costs $500 to $4,000 depending on the scope and methods used. While this isn't required before selling, having a clean engineering report can be a significant selling point — especially for buyers who would otherwise walk away from uncertainty.
Five Things to Do Before You List a Sinkhole-Affected Home
1. Compile every piece of documentation. Insurance claims, remediation reports, engineering evaluations, contractor invoices, permits — gather everything. A buyer who sees organized, complete records is more likely to close than one who encounters gaps and unanswered questions.
2. Get a current engineering assessment. If the sinkhole was repaired years ago, a current evaluation from a licensed geotechnical engineer can confirm that the remediation is holding and that no new activity has developed. This is the single most effective step you can take to reassure a buyer and their lender.
3. Price the disclosure into your asking price. Sinkhole history affects market value. Pricing as if the history doesn't exist only leads to failed deals when the appraisal comes in low or the buyer's lender requires a discount. Honest pricing from the start attracts serious buyers.
4. Understand your insurance options before listing. If your current policy doesn't include sinkhole loss coverage, investigate what coverage is available. A buyer's lender may require evidence of insurability before approving the loan, and knowing the insurance landscape in advance lets you address questions proactively.
5. Evaluate all your selling paths — not just the traditional one. A traditional listing can work for a sinkhole-affected property, but the timeline is often longer, the buyer pool is smaller, and the risk of deals falling through is higher. Understanding the full range of options — including cash offers, investor sales, and auction — before you commit to one path gives you more control over the outcome.
The Bottom Line: Sinkholes Don't Make Your Home Unsellable — But They Change Everything About How You Sell It
A sinkhole disclosure is not a death sentence for a home sale. Properties with sinkhole history sell every day in Florida. But they sell differently. The disclosure rules are strict. The insurance landscape is complicated. The buyer financing path is narrow. And the margin for error — a missing report, an undisclosed claim, a buyer whose lender backs out — is much smaller than in a conventional sale.
Sellers who succeed are the ones who understand the rules, prepare their documentation, price honestly, and choose a selling path that accounts for the complications their property carries. That might be a traditional listing with an agent who specializes in sinkhole properties. It might be a direct cash sale that bypasses the lender and insurance obstacles entirely. The right choice depends on your timeline, your financial situation, and how much uncertainty you can absorb.
What doesn't work is pretending the sinkhole isn't there. Florida law says you have to disclose it. The public records prove it exists. And a buyer who discovers it after closing has legal recourse against you. Honesty isn't just the ethical choice — it's the only strategy that protects you.
This article is for educational purposes and does not constitute legal, insurance, or real estate advice. Consult a licensed Florida real estate attorney and a qualified geotechnical engineer for guidance specific to your property.
HOW DO YOU FEEL ABOUT FASHION?
COMMENT OR TAKE OUR PAGE READER SURVEY
Featured
Adam Wadi’s professional journey spans nearly two decades of leadership in vocational education, corporate strategy, and business growth consulting.